BAM Banner
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
BAM MARKET WRAP
April 29, 2016
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
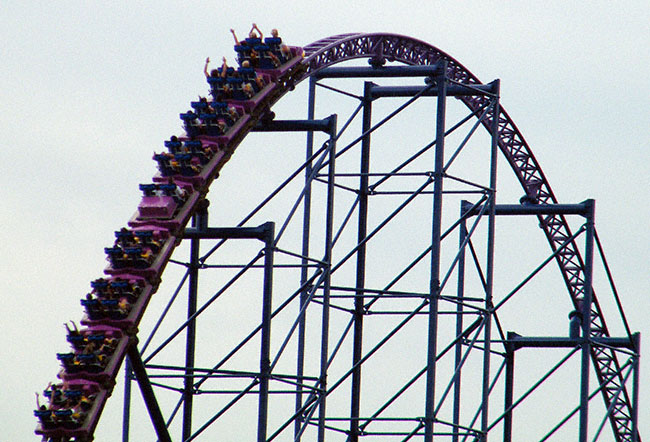
TOP OF THE ROLLER COASTER
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~  

WHERE WE HAVE BEEN 
 
Despite the wild swings of the markets this year, we are just about where we started.  The Dow and S&P have fared best with modest gains of 1 to 2%.  Meanwhile, the tech laden NASDAQ has logged a disappointing year to date 4% loss.  Earnings continue to roll in and have failed to impress despite lowered expectations.  Yesterday, first quarter GDP was reported a .5% seasonally adjusted annual rate.  It was the worst reading in over 2 years and lends credence to what many economists have been saying - the US and world economies are slowing.  In year's past, a weak quarter has led to a rebound in the next quarter.  Hopefully, that trend will continue and the economic malaise will abate.  
 
WHERE WE ARE HEADED 
 
As our weekly missives have been charting, the major indices are all at the top of their 18-month trading range.   It will take some catalyst to push the indices above the top of the range and the most logical path would be a sidewise to downward trending market.  That said, this market has been less than logical over the last few years.  The wild card continues to be government interventions around the world.  The Fed met earlier this week and to no one's surprise made no change to interest rates.  Their statement did, however, reference the slowing economy and the need to be measured in any increases.  The GDP report may well have pushed any further rate increase beyond the expected June date.   Despite the sideways markets there are pockets of growth and opportunities.  Various bond funds have thrived in the current market with high yield bonds among the leaders.  For the month of April, the Merrill Lynch High Yield index was up 4% and over 7% for the year.  There are other areas of the market that have also received our attention.   We remain wary of market weakness but like how our portfolios are acting currently.   We will continue to monitor and make changes as the market dictates.

 
HOW WE ARE DOING

We have made significant changes to our portfolios over the course of the month.  We are currently nearly fully invested in a combination of bond funds with a small position in energy funds.  Energy has been pummeled over the last 2 years but seems to have found a bottom and is currently trending up nicely.  There is lots of room to the upside but the sector isn't out of the woods yet.  We continue to seek out opportunities in this challenging market but do like how our portfolio is responding to the day-to-day gyrations.  


~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

 
Tidbits
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~ ~~~~~~~~~~~
   
HUGE NUMBERS - The US stock market was worth $23.6 trillion as of 12/31/15.  The S&P 500 comprises 80% of the total US stock market capitalization as of 12/31/15, equal to $18.77 trillion.  The US bond market (including treasury, municipal, corporate, mortgage and asset-backed debt) was worth $39.92 trillion as of 12/31/15 (source: Securities Industry and Financial Markets Association).  

CAN'T WAIT - 35% of American males and 40% of American females elect to take their Social Security retirement benefits at age 62, the earliest age at which a worker has access to benefits albeit at a permanent 25% discount (source: Social Security Administration).

TIME WILL TELL - More than 2 of 3 Millennials surveyed (68%) in early March 2016 believe that they will be "more successful" professionally than either of their parents were in their working careers.  "Millennials" are defined as the 75 million Americans ages 19-35 in 2016, i.e., individuals born from 1981-1997 (source: Rock the Vote Poll).        

WAY MORE - The average price of "brand-name" prescription drugs increased by +16.2% in 2015.  Inflation, as measured by the CPI, increased +0.7% in 2015 (source: Express Scripts annual drug trend report).

BEEN THERE, DONE THAT - The 5 Eurozone countries (i.e., the countries that use the Euro as their common currency) that received a financial bailout between February 2010 and July 2012 were Greece, Ireland, Portugal, Spain and Cyprus.  As of 4/28/16, Greece is the only country of the 5 that has yet to exit its bailout program as structured by its European creditors (source: BAM Research). 
      
 ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~


With the coming of May, our youngest (Sarah) will be moving back home for the summer.  Kelly and I have really enjoyed our empty nesting but it will be great to have her back under our roof.  We have been trying to squeeze in as much empty nesting fun as we can over the last few weeks.  Just this week we have eaten out at our favorite pizza place (Nashville Pizza Company), our favorite Mexican (Las Palmas) - great margaritas!, and last night we splurged and had Hattie B's hot chicken and a dipped cone from Bobbie's Dairy Dip.  We'll resume our diet next week!  Carter will be staying in Knoxville for the summer, working and taking a few classes.  Sam and Nancy will be on duty to make sure he is well taken care of.    We continue to be in the midst of wedding planning with our oldest Emily - the date draws near and all are excited for her.   We trust that your summer plans are taking shape and that they are full of adventure and shared with those you love.


Sam and Bo


Your financial partner for twenty years and counting because managing your money never gets old.


We continue to make posts to our blog throughout the week so check it regularly if you want to see our thoughts.  You can access it by following the link below.  


THE GREATEST COMPLIMENT

In these uncertain times, a trusted financial adviser is more important than ever.  Whatever comes over the upcoming months and quarters, the markets are certain to have lots of volatility and wild swings.  Europe, the US economy and dysfunction in Washington, and continued trouble in Iran and the Middle East to name just a few.  If you have family, friends and neighbors that may benefit from our services, would you please forward this email and/or provide our contact information to them.  We purposefully do not spend time marketing our services so that we can devote all of our resources to managing your assets.  Thank you to all who have provided us referrals - it truly is the greatest compliment you can give us.      


BAM MARKET WRAP EXTENDED
EDITION
 
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

Remember to visit our blog for market comments and observations in between newsletters.  We try to provide a few comments in between newsletters and certainly when there is a particularly interesting market day.  You can access it by clicking here. 

Quick Links
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Investing Philosophy
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Contact Information
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
BAM Logo

Knoxville Office

Sam Bills - (865) 525-1329

Nashville Office
Bo Bills - (615) 371-5928

~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
NAAIM Newsletter Award

Published by Sam C. Bills, Jr.  Copyright © 2008 Bills Asset Management.  All rights reserved.

BAM Market Wrap is produced and distributed regularly via email by Sam C. Bills, Jr. of Bills Asset Management  3001 Flagstone Drive, Franklin, TN 37069 Phone (615) 371-5928 Fax (615) 250-4903 - www.Billsasset.com

Bills Asset Management  is an independent registered investment advisor (RIA) not associated with any financial institution.  Data used in this publication is gathered from reliable sources, although completeness and accuracy cannot be guaranteed.  Performance results do not take into account any tax consequences and are not predictive of future results.  This publication does not give any specific investment advice, does not provide financial planning services, or consider any individual's financial situation, needs or goals.  This publication may not be reproduced or retransmitted in whole or in part without the consent of the author, Sam C. Bills, Jr.


Important Disclosure Information


Bills Asset Management ("BAM") composite performance results represent time-weighted actual performance results for continuously managed BAM accounts, which individual accounts BAM believes to be representative of its investment management process (i.e. mutual funds and exchange traded funds) for each specific strategy during the corresponding time period.  The composite performance results reflect the reinvestment of dividends and other account earnings, and are net of applicable account transaction and custodial charges, and the separate fees assessed directly by each unaffiliated mutual fund and exchange traded fund holding that comprised each account, and the maximum investment advisory fee that the accounts would have incurred (by applying BAM's current investment advisory fee as set forth in its current written disclosure statement) during the corresponding time periods.


Please Note:  Past performance may not be indicative of future results.  Therefore, no current or prospective client should assume that future performance will be profitable, equal the performance results reflected, or equal any corresponding historical benchmark index.  The historical index performance results for all historical benchmark indices do not reflect the deduction of transaction and custodial charges, or the deduction of an investment management fee, the incurrence of which would have the effect of decreasing indicated historical performance results.  The historical performance results for all indices are provided exclusively for comparison purposes only, so as to provide general comparative information to assist an individual client or prospective client in determining whether the performance of BAM program meets, or continues to meet, his/her investment objective(s).  A corresponding description of each index is available from BAM upon request.  It should not be assumed that BAM account holdings will correspond directly to any such comparative benchmark index.  The BAM performance results do not reflect the impact of taxes.


For reasons including variances in the investment management fee incurred, market fluctuation, the date on which a client engaged BAM's investment management services, and any account contributions or withdrawals, the performance of a specific BAM client's account may have varied substantially from the indicated portfolio performance results.


In the event that there has been a change in a client's investment objectives or financial situation, he/she/it is encouraged to advise BAM immediately.  Different types of investments and/or investment strategies involve varying levels of risk, and there can be no assurance that any specific investment or investment strategy (including the investments purchased and/or investment strategies devised or undertaken by BAM will be profitable. 


Information pertaining to BAM's advisory operations, services, and fees is set forth in BAM's current disclosure statement, a copy of which is available from BAM upon request.  Performance results have been compiled solely by BAM, are unaudited, and have not been independently verified.  BAM maintains all information supporting the performance results in accordance with regulatory requirements.