|
|
|
|
 |
| Click to View |
|
Happy New Year everyone, we are happy to announce our latest research from IHL Group
2017 Retail IT Market Leaders - Competitive Profiles
that will provide great preparation for the NRF Show. This study looks at 30 top Retail IT Companies and who retailers are planning to increase business with or decrease business with in 2017. It answers some of the questions like:
- Who is really winning among IT Vendors?
- Who are customers increasing business with in 2017, when does SAP win verses Oracle verses NCR verses SalesForce/Demandware or Aptos or Toshiba?
- When do they lose business?
- What are the highest priorities for each vendor's customers?
- Are their customers growing faster than the market, increasing IT Spend or decreasing?
- Are they increasing store counts or decreasing?
- How fast are they moving to the cloud?
- Are there customers more likely to be investing in Upgrades to existing technologies or Transformational IT Spend to compete with Amazon?
- And finally, how do they drive innovation - internally, through partners or innovation labs?
This research looked at 83 retailers and top vendors. Last year this was limited to Store Systems vendors, but this year it has been extended to include enterprise vendors as well as consultants and services companies.
Vendors evaluated and what their customers say who they are increasing/decreasing business with are
Accenture,
Amazon,
Aptos,
AT&T,
Capgemini,
Cisco,
Demandware /SalesForce,
EarthLink,
Fujitsu,
HP Inc.,
HP Enterprise,
IBM,
Infor,
Infosys,
JDA,
Manhattan,
Microsoft,
Netsuite,
NCR,
Oracle,
PwC,
SAP,
TCS,
Toshiba Global Commerce
Tyco Retail/ShopperTrack,
Verizon,
Wipro,
Zebra/Motorola.
The research is available immediately as part of a Retail Executive Advisory Program Subscription or individually. For more information, see the website, respond to this email or contact us at +1.615.591.2955.
|
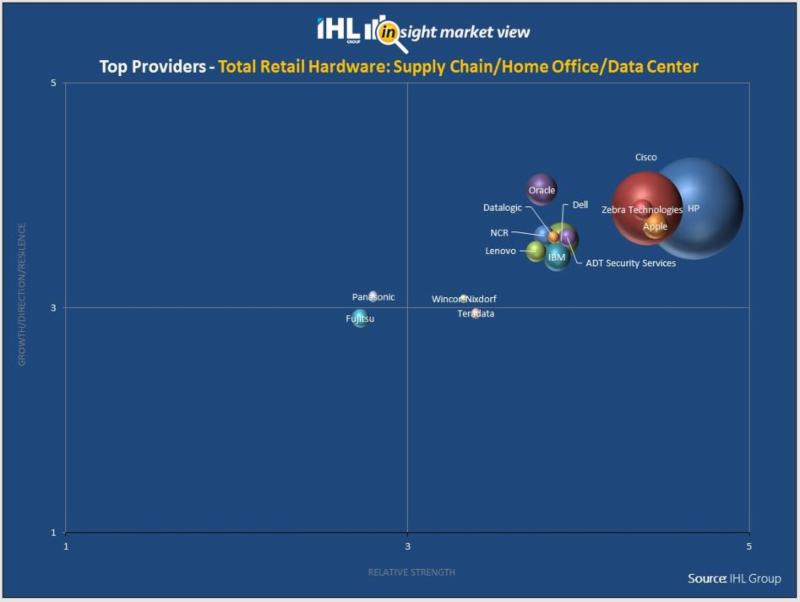
Overall, the
$55b USD Retail Hardware Market is relatively flat in comparison to Software, Services, and SaaS, but this belies the monstrous changes in individual markets and hardware types. Without question, in mature retail markets we are seeing a dramatic shift at the data center and store level in terms of reduction of servers.
The IT spend here is shifting from spending on Hardware to spending on SaaS and IaaS (Infrastructure-a-Service). This net loss to hardware spend (and sales of hardware to end retailers) is balanced by two situations we are currently monitoring:
a) Emerging Markets - The ever-burgeoning middle class in emerging markets continues to increase the demand for mature retail, and retailers are aggressively expanding. In many cases, they are deploying POS technologies at the store level for the first time.
b) New Hardware - Several other hardware technologies are experiencing rapid growth, such as Mobile POS, Kiosks and Digital Signage.
No two regions are the same and no two segments in those regions are the same. For instance, fixed POS in Department Stores in North America are declining as stores decrease and more touchpoints move to Mobile POS devices. But in the QSR and Entertainment markets we see rapid expansion as these stores deploy POS for the first time.
Vendors ranked in this research include the following:
ADT, Apple, Checkpoint, Cisco, Datalogic, Dell, Diebold-Nixdorf, Epson, Fujitsu, Gilbarco, HP, IBM, Ingenico, Lenovo, NCR, Oracle, Panasonic, Teradata, Toshiba Global Commerce Solutions, VeriFone, Zebra.
|
|
|
| |
|