BAM Banner
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
BAM MARKET WRAP
October 28, 2016
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
October Surprises
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~  

WHERE WE HAVE BEEN 
 
October comes to a close on Monday and despite its history of positive results has been a less than stellar month for the markets.  As of today, the S&P is down a little over 1.6%.  More telling, however, is the performance of the small caps - the Russell 2000 is down almost 5% month to date.  As we have noted here many times, small caps are often the canary in the coal mine as they usually lead to the upside and to the downside.  Certainly small caps will need to stabilize and head up for the markets to gain any traction over the coming traditionally strong market time.   This has been a go nowhere market with the S&P virtually unchanged since March 2015.  

WHERE WE ARE HEADED 
 
While November through April are traditionally the strongest 6 months of the year, this year could prove more challenging.  With a contentious election and two unpopular candidates, it remains unclear how the market will respond to election results.  The market likes certainty so the uncertainty of the election (especially as polls tighten and now with the reopening of the FBI's Clinton email investigation) could prove to be a stumbling block leading up to the election and will certainly lead to increased volatility.  Developments that would lead to either Democratic (Clinton takes the White House and Democrats retake the House and Senate) or Republican (Trump takes the White House and Republicans retain the House and Senate) control would likely lead to a sell-off as the markets do prefer divided government.  Neither of those scenarios are baked in the current market as polls indicate the Senate will move back to the Democrats and the House will remain Republican ensuring divided government regardless of who takes the presidency.  As if the election was not enough, the Fed will also hold policy meetings next week and again in December.  It is assured that the Fed will be very careful next week in their wording and actions so as not to affect the election but the December meeting will prove more interesting.  There is a growing split among the Fed Governors on whether or not to raise interest rates so that uncertainty remains as well.  All that to say, we remain cautiously optimistic over the coming few months but there are a number of pitfalls and surprises that could stall this market so investors would be wise to remain vigilant in their investments.  

HOW WE ARE DOING

We have made no changes to our portfolios over the last month.  Our low volatility portfolio has continued to prove to be a good approach with small gains in October as the market slides.  With volatility likely to increase over the coming weeks, we do not anticipate making any significant changes in the near term.  However, we are constantly evaluating our portfolio to either upgrade existing funds or move to cash should the markets get messy.  

~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Tidbits
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~ ~~
NIFTY NOVEMBER - November has been the 4th best performing month for the S&P 500 since 1991.  Over the last 25 years (1991-2015), the S&P 500 has gained an average total return of +1.38% during November.  Over the entire period, 18 of 25 Novembers have been up.  The S&P 500 consists of 500 stocks chosen for market size, liquidity and industry group representation.  It is a market value weighted index with each stock's weight in the index proportionate to its market value (source: BAM Research).

HOME DEBT - The average loan-to-value ratio in the US housing market as of 6/30/08 was 55%, i.e., the average US home mortgage had 45% of equity behind it.  The average loan-to-value ratio in the US housing market as of 6/30/16 was 43%, i.e., the average US home mortgage had 57% of equity behind it (source: Federal Reserve).  

NO TAXES - 54.4% of the American taxpayers (50.4 million out of 92.7 million returns) that reported adjusted gross income less than $50,000 during tax year 2014 legally did not pay any federal income tax (source: Internal Revenue Service).  

NOT A PENNY - 0.1% of the American taxpayers (443 out of 410,298 returns) that reported adjusted gross income of at least $1 million during tax year 2014 legally did not pay any federal income tax (source: Internal Revenue Service).    

NATIONAL EXPENDITURES - 61% of the $3.854 trillion of total outlays for the US government during the recently completed fiscal year 2016 were in just 4 categories - Social Security ($916 billion), National Defense ($595 billion), Medicare (also $595 billion) and Net Interest Expense ($241 billion).  Total outlays increased by +4.5% on a year-over-year basis, up $166 billion (source: Treasury Department). 
      
 ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
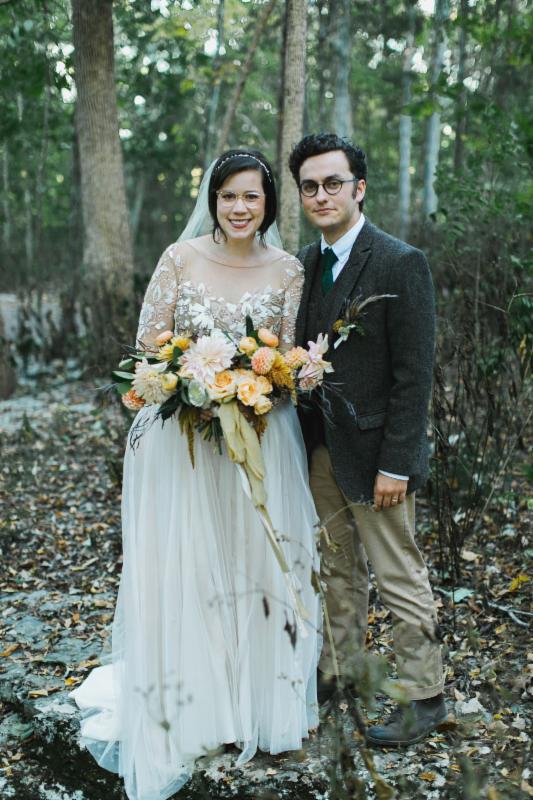
October 8th was a beautiful and wonderful day as Emily Bills became Mrs. Emily Handy. Emily stole the show and looked absolutely stunning in her wedding gown (Jake looked good too!).  Kelly worked tirelessly to make sure that Saturday went off without any hitches (save Emily and Jake) and did a phenomenal job.  The wedding was spectacular!  A beautiful fall day turned into a cool fall evening full of good food, lots of laughter, lots of music and lots of dancing!  It really could not have gone any better and by all accounts everyone agreed.   We are still awaiting pictures from the photographer but I think this one will be among my favorites!   


One down and two to go!   


 Sam and Bo


Your financial partner for twenty years and counting because managing your money never gets old.


We continue to make posts to our blog throughout the week so check it regularly if you want to see our thoughts.  You can access it by following the link below.  


THE GREATEST COMPLIMENT

In these uncertain times, a trusted financial adviser is more important than ever.  Whatever comes over the upcoming months and quarters, the markets are certain to have lots of volatility and wild swings.  Europe, the US economy and dysfunction in Washington, and continued trouble in Iran and the Middle East to name just a few.  If you have family, friends and neighbors that may benefit from our services, would you please forward this email and/or provide our contact information to them.  We purposefully do not spend time marketing our services so that we can devote all of our resources to managing your assets.  Thank you to all who have provided us referrals - it truly is the greatest compliment you can give us.      


BAM MARKET WRAP EXTENDED
EDITION
 
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

Remember to visit our blog for market comments and observations in between newsletters.  We try to provide a few comments in between newsletters and certainly when there is a particularly interesting market day.  You can access it by clicking here. 

Quick Links
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Investing Philosophy
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Contact Information
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
BAM Logo

Knoxville Office

Sam Bills - (865) 525-1329

Nashville Office
Bo Bills - (615) 371-5928

~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
NAAIM Newsletter Award

Published by Sam C. Bills, Jr.  Copyright © 2008 Bills Asset Management.  All rights reserved.

BAM Market Wrap is produced and distributed regularly via email by Sam C. Bills, Jr. of Bills Asset Management  3001 Flagstone Drive, Franklin, TN 37069 Phone (615) 371-5928 Fax (615) 250-4903 - www.Billsasset.com

Bills Asset Management  is an independent registered investment advisor (RIA) not associated with any financial institution.  Data used in this publication is gathered from reliable sources, although completeness and accuracy cannot be guaranteed.  Performance results do not take into account any tax consequences and are not predictive of future results.  This publication does not give any specific investment advice, does not provide financial planning services, or consider any individual's financial situation, needs or goals.  This publication may not be reproduced or retransmitted in whole or in part without the consent of the author, Sam C. Bills, Jr.


Important Disclosure Information


Bills Asset Management ("BAM") composite performance results represent time-weighted actual performance results for continuously managed BAM accounts, which individual accounts BAM believes to be representative of its investment management process (i.e. mutual funds and exchange traded funds) for each specific strategy during the corresponding time period.  The composite performance results reflect the reinvestment of dividends and other account earnings, and are net of applicable account transaction and custodial charges, and the separate fees assessed directly by each unaffiliated mutual fund and exchange traded fund holding that comprised each account, and the maximum investment advisory fee that the accounts would have incurred (by applying BAM's current investment advisory fee as set forth in its current written disclosure statement) during the corresponding time periods.


Please Note:  Past performance may not be indicative of future results.  Therefore, no current or prospective client should assume that future performance will be profitable, equal the performance results reflected, or equal any corresponding historical benchmark index.  The historical index performance results for all historical benchmark indices do not reflect the deduction of transaction and custodial charges, or the deduction of an investment management fee, the incurrence of which would have the effect of decreasing indicated historical performance results.  The historical performance results for all indices are provided exclusively for comparison purposes only, so as to provide general comparative information to assist an individual client or prospective client in determining whether the performance of BAM program meets, or continues to meet, his/her investment objective(s).  A corresponding description of each index is available from BAM upon request.  It should not be assumed that BAM account holdings will correspond directly to any such comparative benchmark index.  The BAM performance results do not reflect the impact of taxes.


For reasons including variances in the investment management fee incurred, market fluctuation, the date on which a client engaged BAM's investment management services, and any account contributions or withdrawals, the performance of a specific BAM client's account may have varied substantially from the indicated portfolio performance results.


In the event that there has been a change in a client's investment objectives or financial situation, he/she/it is encouraged to advise BAM immediately.  Different types of investments and/or investment strategies involve varying levels of risk, and there can be no assurance that any specific investment or investment strategy (including the investments purchased and/or investment strategies devised or undertaken by BAM will be profitable. 


Information pertaining to BAM's advisory operations, services, and fees is set forth in BAM's current disclosure statement, a copy of which is available from BAM upon request.  Performance results have been compiled solely by BAM, are unaudited, and have not been independently verified.  BAM maintains all information supporting the performance results in accordance with regulatory requirements.