BAM Banner
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
BAM MARKET WRAP
April 28, 2017
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
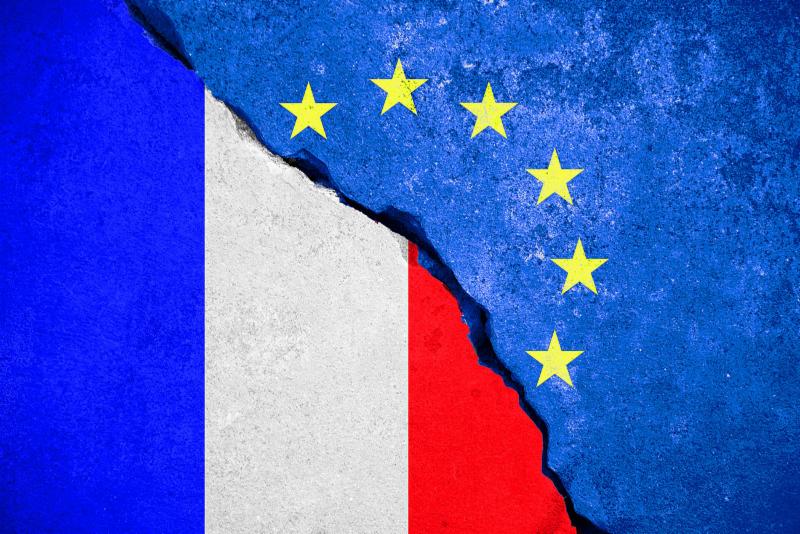
Frexit Averted! (For Now)
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~  

WHERE WE HAVE BEEN 
 
This morning excellent earnings reports from the technology sector was counteracted by a meager GDP report which showed first quarter annualized growth of .7%.   The GDP report led traders to temper their enthusiasm for the generally better than expected earnings reports of the last couple of weeks.  It should be noted that since 2011 first quarter GDP growth has averaged .9% compared with 2.4% in each of the other quarters.  So perhaps it is just a seasonal anomaly.  In any event, GDP growth will need to improve significantly to justify the current valuations in the market.  If not, then the long awaited bear market may come sooner than many expect.  After a lackluster start to the month where the S&P declined, the market surged after the French elections last weekend.  International markets also rallied strongly as the prospect of a Frexit became less likely.  

WHERE WE ARE HEADED 
 
The coming week will see another possibility of a government shut-down.  Today, Congress passed a one-week resolution to fund the government through next Friday.  If a longer-term deal is not made, then the markets will feel the pain of the increased government uncertainty.  Earnings reports will continue to drive day to day market activity.  With the surge earlier this week, the major indices all broke out of their short term down-trends setting the stage for a rally back up to the highs of the year.  The NASDAQ has already eclipsed those highs so it would not be surprising for the other indices to follow suit.  We are getting close to the traditionally weak market months so any surprises could easily curtail the rally.   The markets are again looking favorable.  As is always the case, things can change quickly so we remain nimble.  

HOW WE ARE DOING

Over the last couple of weeks, we have made significant adjustments to our portfolios.  We have upgraded some of our more conservative holdings to ones with more upside potential.  Specifically, we have moved out of our floating rate bond holdings and have moved those funds into US small cap and multi-country international funds.  As you are well aware, markets can change on a dime so we will continue to adjust portfolios as market conditions warrant.   


~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Tidbits
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~ ~~
NOT THE BEST - The average US investor that manages their own investments has produced an annualized rate of return over the last 30 years that is equal to just one-third of the average return produced by the S&P 500 over the same 3 decade time period due to bad timing on the part of the investor (e.g., investing at bull market tops or selling at bear market bottoms), diversifying with bonds, and the impact of trading fees (source: Dalbar).  

NOT ENOUGH WORKERS - 73% of contractors surveyed in January 2017 said they had "a hard time filling salaried or hourly craft construction jobs" in 2016 (source: Associated General Contractors of America).

A LOT MORE RENTERS - As of the end of 2016, there were 118.6 million households in the United States, split 64/36 between homeowners (75.6 million) and renters (43.0 million).  Since the end of 2011 (i.e., 5 years earlier), the number of homeowners (75.3 million as of 12/31/11) has increased by just +300,000 while the number of renters (38.8 million as of 12/31/11) has increased by +4.2 million (source: Census Bureau). 

WHERE THE MONEY COMES FROM - Property taxes represent 31.3% of the total tax revenue collected by states, greater than the 23.3% of tax revenue collected from sales taxes and the 22.9% of tax revenue that comes from individual state income taxes (source: Tax Foundation). 

BEARS FOLLOW BULLS - The average decline for the S&P 500 during the 11 bear markets that have taken place since the end of World War II is 34% (source: BAM Research).  
  
 
 ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
I recently entered the world of academia embarking on teaching a night class a few times a year at Belmont College.  As I have gotten older and a little grayer, my peers and clients have been asking more and more questions about social security and retirement planning.  When I realized, I didn't always have a good answer, I took it upon myself to educate myself and became a National Social Security Association Certificant.  I endured rigorous training and testing to achieve the designation and am proud of the accomplishment.  More importantly it allows me to better serve our existing clients and the community at large.  Teaching has been more difficult than I imagined and a very humbling and rewarding experience.  If you are in the Nashville area and are interested in the class or have friends or family that might be interested, please let me know as I am scheduling my Fall classes now.  Following in the educator footsteps of both my father and father-in-law, it is yet another example of the apple not falling far from the tree! 


DID YOU KNOW...

That if your 18 year old or older child is involved in a medical emergency you might not be able to find out their condition or make medical decisions on their behalf?  I have mentioned this in these pages before but it bears repeating.  If you have a college student or even a single young adult, you should strongly consider getting them to sign a health care proxy or even a durable power of attorney to allow you to make health care and other decisions for them if they are unable to make those decisions themselves.  I imagine you would make better informed decisions than a disinterested court.  You can read about it here and can get a copy of a state specific health care proxy here.


 Sam and Bo


Your financial partner for twenty years and counting because managing your money never gets old.


We continue to make posts to our blog throughout the week so check it regularly if you want to see our thoughts.  You can access it by following the link below.  


THE GREATEST COMPLIMENT

In these uncertain times, a trusted financial adviser is more important than ever.  Whatever comes over the upcoming months and quarters, the markets are certain to have lots of volatility and wild swings.  Europe, the US economy and dysfunction in Washington, and continued trouble in Iran and the Middle East to name just a few.  If you have family, friends and neighbors that may benefit from our services, would you please forward this email and/or provide our contact information to them.  We purposefully do not spend time marketing our services so that we can devote all of our resources to managing your assets.  Thank you to all who have provided us referrals - it truly is the greatest compliment you can give us.      


BAM MARKET WRAP EXTENDED
EDITION
 
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

Remember to visit our blog for market comments and observations in between newsletters.  We try to provide a few comments in between newsletters and certainly when there is a particularly interesting market day.  You can access it by clicking here. 

Quick Links
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Investing Philosophy
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Contact Information
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
BAM Logo

Knoxville Office

Sam Bills - (865) 525-1329

Nashville Office
Bo Bills - (615) 371-5928

~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
NAAIM Newsletter Award

Published by Sam C. Bills, Jr.  Copyright © 2008 Bills Asset Management.  All rights reserved.

BAM Market Wrap is produced and distributed regularly via email by Sam C. Bills, Jr. of Bills Asset Management  3001 Flagstone Drive, Franklin, TN 37069 Phone (615) 371-5928 Fax (615) 250-4903 - www.Billsasset.com

Bills Asset Management  is an independent registered investment advisor (RIA) not associated with any financial institution.  Data used in this publication is gathered from reliable sources, although completeness and accuracy cannot be guaranteed.  Performance results do not take into account any tax consequences and are not predictive of future results.  This publication does not give any specific investment advice, does not provide financial planning services, or consider any individual's financial situation, needs or goals.  This publication may not be reproduced or retransmitted in whole or in part without the consent of the author, Sam C. Bills, Jr.


Important Disclosure Information


Bills Asset Management ("BAM") composite performance results represent time-weighted actual performance results for continuously managed BAM accounts, which individual accounts BAM believes to be representative of its investment management process (i.e. mutual funds and exchange traded funds) for each specific strategy during the corresponding time period.  The composite performance results reflect the reinvestment of dividends and other account earnings, and are net of applicable account transaction and custodial charges, and the separate fees assessed directly by each unaffiliated mutual fund and exchange traded fund holding that comprised each account, and the maximum investment advisory fee that the accounts would have incurred (by applying BAM's current investment advisory fee as set forth in its current written disclosure statement) during the corresponding time periods.


Please Note:  Past performance may not be indicative of future results.  Therefore, no current or prospective client should assume that future performance will be profitable, equal the performance results reflected, or equal any corresponding historical benchmark index.  The historical index performance results for all historical benchmark indices do not reflect the deduction of transaction and custodial charges, or the deduction of an investment management fee, the incurrence of which would have the effect of decreasing indicated historical performance results.  The historical performance results for all indices are provided exclusively for comparison purposes only, so as to provide general comparative information to assist an individual client or prospective client in determining whether the performance of BAM program meets, or continues to meet, his/her investment objective(s).  A corresponding description of each index is available from BAM upon request.  It should not be assumed that BAM account holdings will correspond directly to any such comparative benchmark index.  The BAM performance results do not reflect the impact of taxes.


For reasons including variances in the investment management fee incurred, market fluctuation, the date on which a client engaged BAM's investment management services, and any account contributions or withdrawals, the performance of a specific BAM client's account may have varied substantially from the indicated portfolio performance results.


In the event that there has been a change in a client's investment objectives or financial situation, he/she/it is encouraged to advise BAM immediately.  Different types of investments and/or investment strategies involve varying levels of risk, and there can be no assurance that any specific investment or investment strategy (including the investments purchased and/or investment strategies devised or undertaken by BAM will be profitable. 


Information pertaining to BAM's advisory operations, services, and fees is set forth in BAM's current disclosure statement, a copy of which is available from BAM upon request.  Performance results have been compiled solely by BAM, are unaudited, and have not been independently verified.  BAM maintains all information supporting the performance results in accordance with regulatory requirements.